Why Some Insurance Underwriters Flag Spray Foam — and What Actually Changes Their Mind
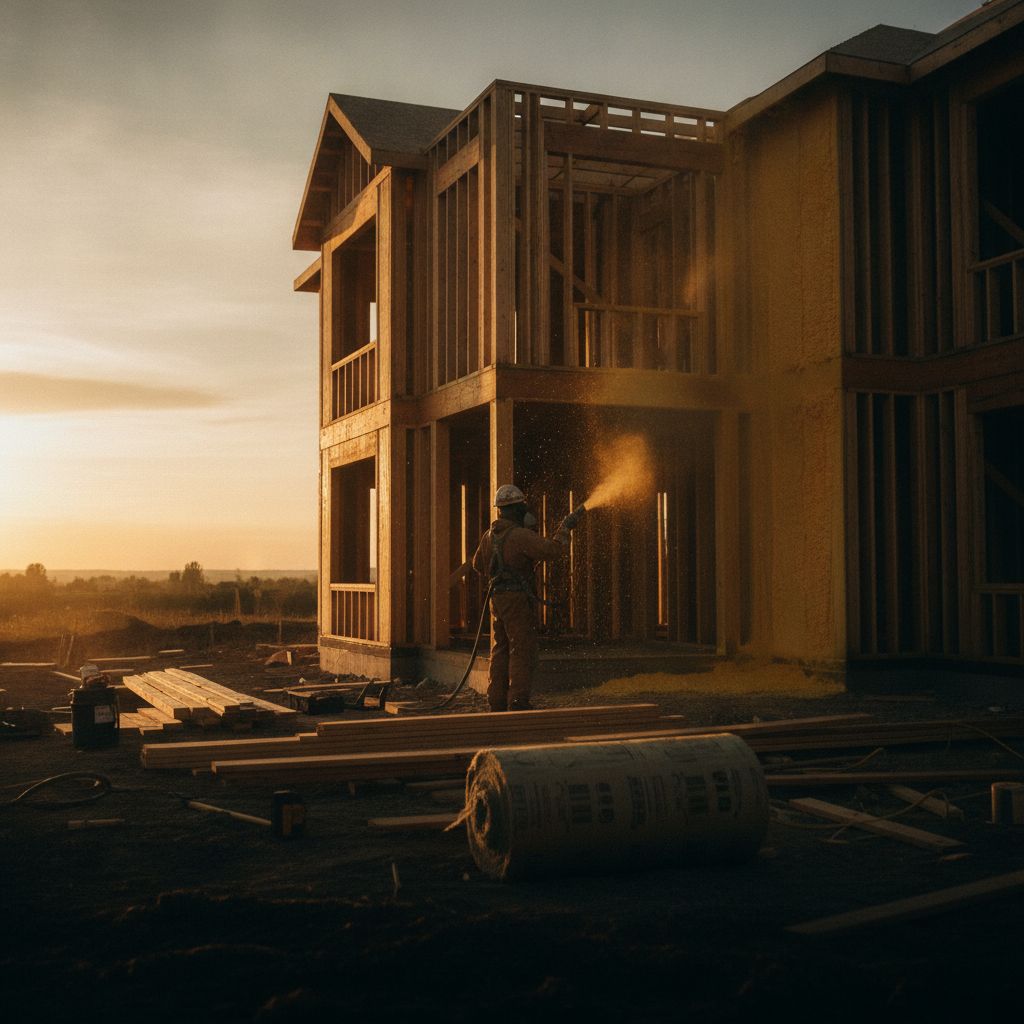
Homeowners are sometimes surprised to find an insurance underwriter asking pointed questions — or in some cases declining coverage — specifically because a home has spray foam insulation in the roof. The reaction feels disproportionate to a material that, correctly installed, performs exactly as intended for decades. The underlying reasoning is more specific than a blanket judgment on the chemistry.
The Core of the Underwriting Concern
Underwriters price risk based partly on claims history, and spray foam has a documented history of claims tied to a specific, identifiable failure pattern: roof deck moisture damage from foam applied over wood that was already wet, or foam installed in an assembly where it trapped moisture that would otherwise have dried out. Those claims are real and expensive when they happen — full roof deck replacement, mold remediation, and sometimes structural repair. An underwriter's caution is a response to that documented claims pattern, not an assessment of spray foam chemistry in the abstract.
The Visibility Problem Compounds It
Beyond the claims history, there's a practical inspection issue: once foam is sprayed against the underside of a roof deck, a visual inspection can no longer confirm the deck's condition without removing the foam. An inspector or underwriter evaluating a home with existing spray foam has no easy way to verify there isn't already hidden damage — which pushes some underwriters toward caution or additional documentation requests by default, independent of whether that particular installation is actually a problem.
What Actually Resolves the Concern
Documentation is the practical answer on both sides of this. For a new installation, that means the installer recording substrate moisture content readings before spraying, confirming the correct product and thickness for the climate and assembly, and providing photos and a completion certificate. For an existing installation being evaluated for a policy, an infrared moisture scan or a documented history from the original installer showing correct application conditions can substitute for the visual inspection access that's no longer possible.
Some underwriters have also become more sophisticated about this over time, moving from a blanket caution toward evaluating documentation on its merits — which is a trend in the right direction as spray foam becomes a more established, better-understood material in the insurance industry specifically.
The Practical Takeaway
If you're installing spray foam, ask your installer to document the process — moisture readings, product used, thickness achieved — and keep that documentation with your home records. If you're buying a home that already has spray foam, ask for that documentation from the seller, or budget for an infrared moisture scan as part of your inspection. Either approach directly addresses the actual underwriting concern instead of leaving it as an open question.
Read the full building science on why spray foam gets flagged, or find a certified installer who documents installations correctly from the start.